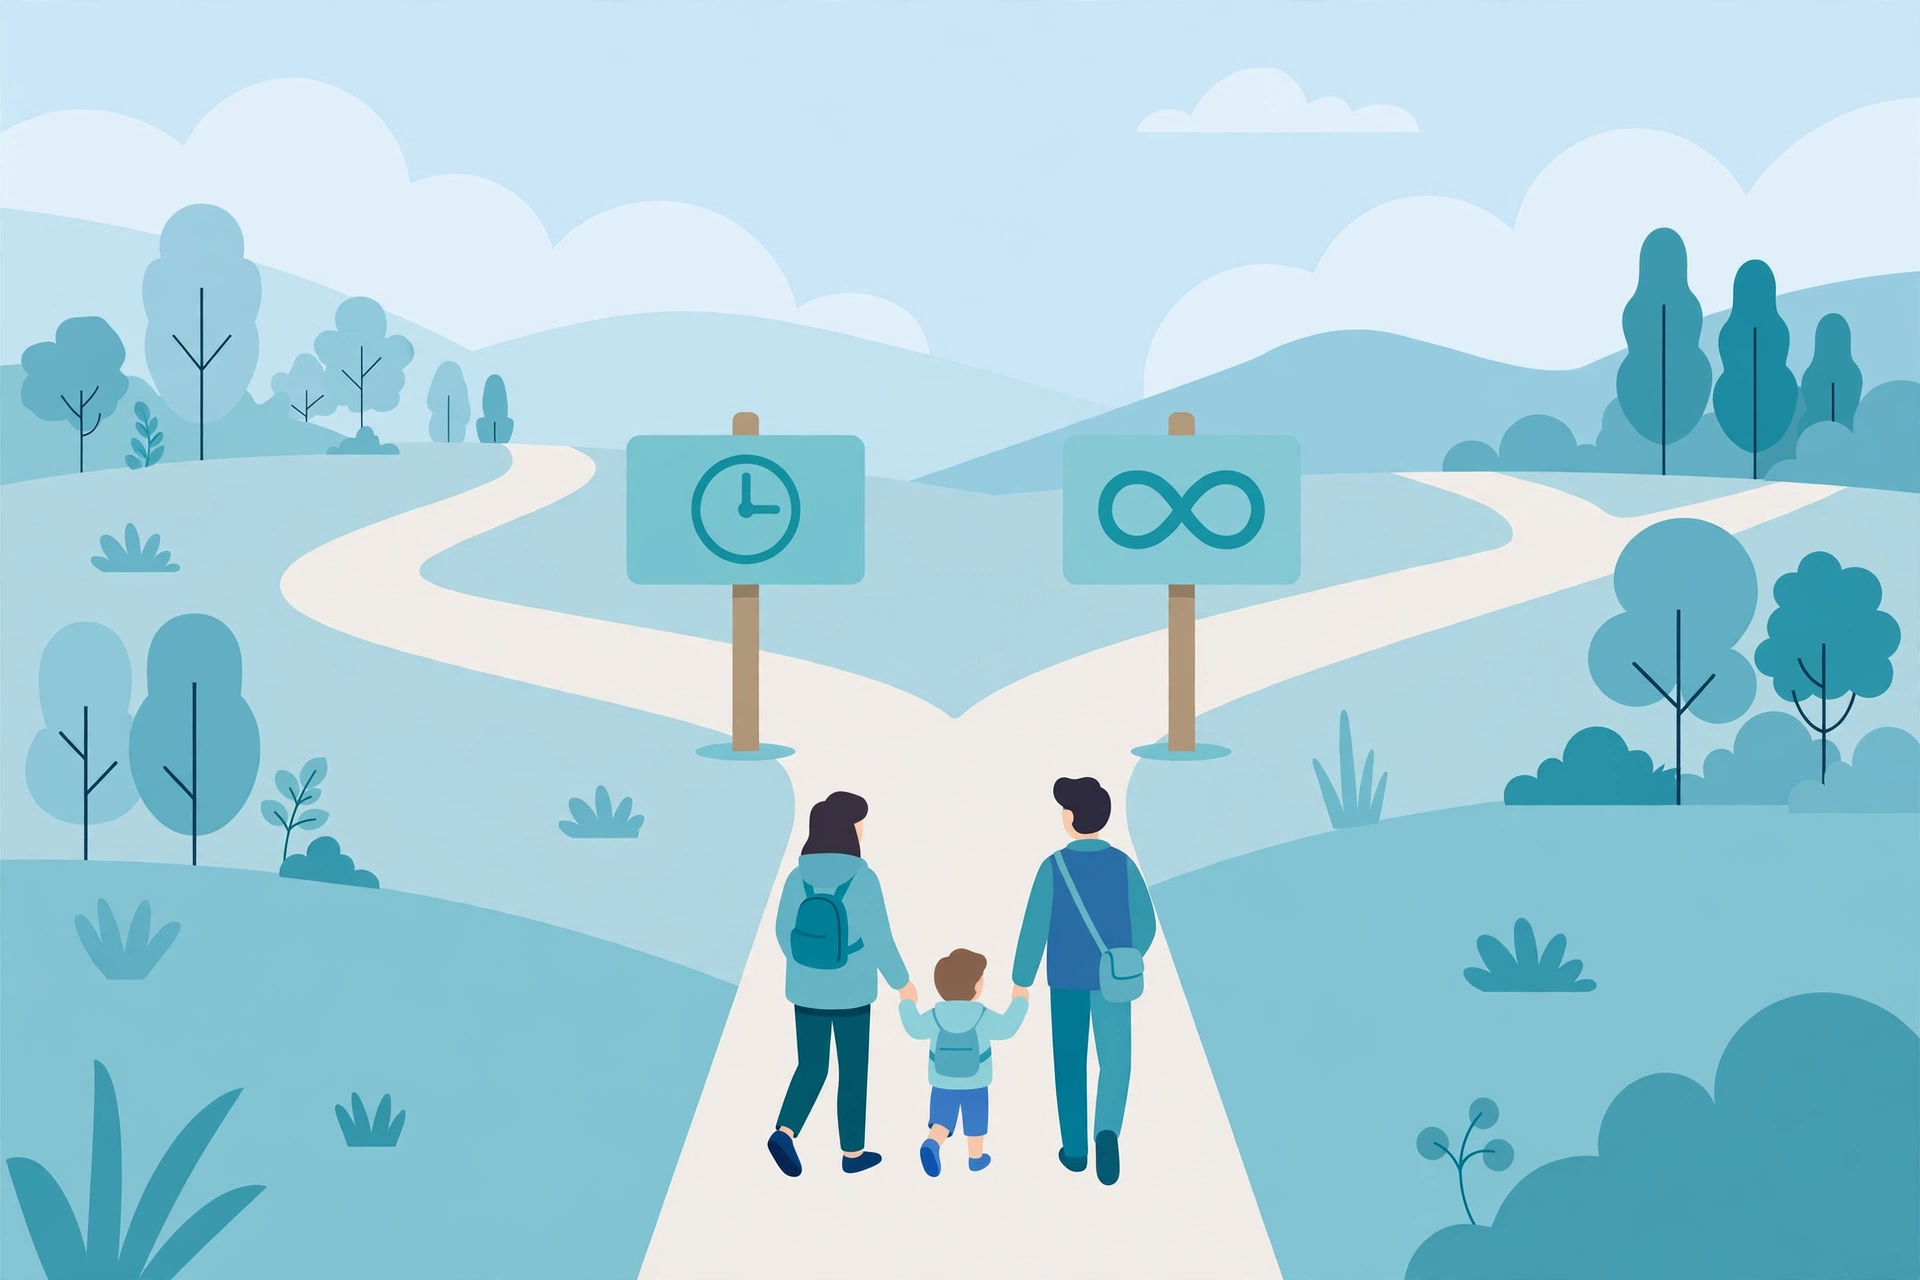
Life insurance comes in many forms, but almost every conversation starts with the same question: term life or whole life? They sound similar, but they work very differently — and the right choice depends entirely on what you’re trying to protect.
Here’s a clear, jargon-free breakdown.
A Quick Refresher: What Is Life Insurance?
Life insurance pays a lump sum of money — the death benefit — to the people you choose (your beneficiaries) when you pass away. People typically buy it so their family can cover the mortgage, replace lost income, pay for education, or handle final expenses without financial hardship.
Both term and whole life do this. The difference is in how long they last, what they cost, and what else they do.
Term Life Insurance: Simple and Affordable
Term life insurance covers you for a set period — commonly 10, 20, or 30 years. If you pass away during the term, your beneficiaries receive the death benefit. If you outlive the term, the coverage ends and there’s no payout.
How it works:
- You choose a coverage amount (say $500,000) and a term length (say 20 years).
- You pay a fixed premium for the whole term.
- If you die during those 20 years, your beneficiaries get $500,000.
- If you’re still alive at year 21, the policy ends.
The big advantage is cost. Because most people outlive their term, insurers can offer large coverage amounts for relatively low premiums — especially if you buy young and healthy. For a young family needing serious protection on a budget, term life is usually the most coverage per dollar.
The tradeoff: it’s temporary. When the term ends, you may need to buy a new policy at an older age — when premiums are higher — or go without coverage.
Whole Life Insurance: Permanent Coverage with a Savings Component
Whole life insurance covers you for your entire life, as long as you keep paying premiums. It never expires. But it does something else too: part of every premium goes into a cash value account that grows slowly over time.
How it works:
- You pay a fixed premium for life.
- The death benefit is guaranteed whenever you pass away.
- A portion of your premiums builds cash value, which you can borrow against or withdraw (usually with conditions and potential fees).
The big advantage is permanence and the cash value. There’s no expiry date to worry about, and the policy doubles as a slow-growing savings vehicle.
The tradeoff is cost. Whole life premiums are typically many times higher than term life for the same death benefit. The cash value also grows slowly, especially in the early years.
Side-by-Side Comparison
| | Term Life | Whole Life | |—|—|—| | Duration | Fixed term (10–30 years) | Entire lifetime | | Premiums | Lower | Much higher | | Death benefit | Paid if you die during the term | Guaranteed whenever you die | | Cash value | None | Builds over time | | Best for | Temporary needs, tight budgets | Permanent needs, estate planning |
Which One Do You Actually Need?
Ask yourself what you’re protecting:
Term life is usually the better fit if:
- You want to cover specific years — while the kids are young, while the mortgage is being paid off.
- You’re on a budget but need a large death benefit.
- You want straightforward, no-frills protection.
Whole life may make sense if:
- You want coverage that can never expire.
- You have lifelong dependents (for example, a child with special needs).
- You’re doing estate planning and want a guaranteed payout.
- You specifically want the cash-value feature and understand its slow growth.
For most young families, financial educators generally point to term life as the practical starting point — it delivers the most protection for the money during the years it’s needed most.
Common Questions
Can I convert term life to whole life later? Many term policies include a conversion option that lets you switch to a permanent policy without a new medical exam, usually within a certain timeframe. Check whether your policy offers this.
What happens when my term ends? You can typically renew (at a higher premium based on your new age), buy a new policy, or let coverage lapse if you no longer need it — for example, once the kids are grown and the mortgage is paid.
Is the cash value in whole life a good investment? It’s best viewed as a conservative savings feature, not a high-growth investment. The growth is slow and steady, and borrowing against it reduces the death benefit if not repaid.
Final Thoughts
Neither option is “better” in the abstract — they solve different problems. Term life is affordable protection for a defined period. Whole life is permanent protection with a savings component at a much higher price.
The right question isn’t which policy wins. It’s: what do the people who depend on you need, and for how long? Answer that, and the choice usually becomes clear.
Disclaimer: This article is for general educational purposes only and is not financial or legal advice. Insurance products and regulations vary by state and provider — always review your specific policy documents or consult a licensed professional for guidance about your situation.